 BanditAI
What Is Form 941-X? — A Guide to Correcting Form 941
Form 941-X, Adjusted Employer’s Quarterly Federal Tax Return or Claim for Refund, is used to correct errors on a previously filed Form 941. It can be used to correct eligible errors involving wages, taxes, adjustments, and other reported information.
Need to correct a previously filed Form 941? Read the complete guide to learn how to identify and correct errors using Form 941-X.
Charles Hardy | Last Updated: September 29, 2026
Form 941-X: Purpose, Instructions, and Filing Tips
- What is Form 941-X?
- How to Amend Form 941?
- Are There Any Changes in Form 941-X for the 2026 Tax Year?
- What information can be corrected using Form 941-X?
- How to fill out Form 941-X?
- How to Correct a Previously Filed Schedule B?
- When is the deadline for filing Form 941-X?
- How to File Form 941-X?
- Where to mail Form 941-X?
- Are there any penalties related to filing Form 941-X?
What is Form 941-X?
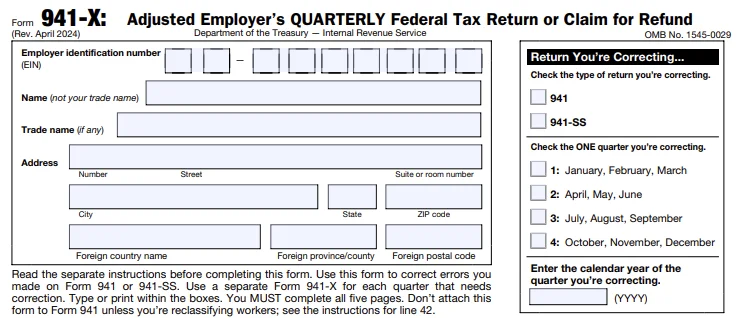
Form 941-X (Adjusted Employer’s Quarterly Federal Tax Return or Claim for Refund) is used to correct any errors made on the 941 Form. If you find an error on a previously filed Form 941, you can correct this error using Form 941-X.
Make sure you file a separate Form 941-X for each tax period only if you have found the errors.
How to Amend Form 941?
If an error is discovered on a previously filed Form 941, use Form 941-X to make the correction. The process depends on whether the original return underreported or overreported employment taxes.
Criteria for Correcting Form 941-X
You need to file Form 941-X if you meet any of the following criteria:
- Underreported Taxes: If less tax was reported than the amount actually owed, file Form 941-X and pay the additional tax due when required. The IRS provides specific timing rules for correcting underreported tax.
- Overreported taxes: If you reported more tax than you owed, you can generally use Form 941-X to adjust the overpayment as a credit or claim a refund or abatement, depending on the circumstances. The IRS provides separate requirements for each process.

To claim a refund or reduce the penalty, you can use Form 843 (Claim for Refund and Request for Abatement).
Are There Any Changes in Form 941-X for the 2026 Tax Year?
Yes. The 2026 Form 941-X includes these key updates:
- Qualified Tips and Overtime: New federal income tax withholding rules apply to qualified tips and qualified overtime compensation. Certain prior-year withholding errors cannot be corrected using Form 941-X.
- Aggregate Return Filers: A new section requires Section 3504 agents, CPEOs, and other applicable third parties filing corrected aggregate returns to identify themselves.
- COVID-19 ERC: New limitations apply to Employee Retention Credit corrections for the third and fourth quarters of 2021, along with an extended assessment period.
- Certain Lines Reserved: Lines 18a, 26a, 30, 31a, 31b, and 32 are reserved for future use because the correction period for these items has generally expired.
For a complete overview of the changes and how they may impact your corrections, refer to our article.
What information can be corrected using Form 941-X?
Form 941-X allows you to correct errors related to wages, employment taxes, tax credits, and other relevant information that was previously reported on IRS Form 941.
The following information can be corrected using Form 941-X:
- Wages, tips, and other compensation
- Income tax withheld from wages, tips, and other compensation
- Taxable social security wages
- Taxable social security tips
- Taxable Medicare wages and tips
- Taxable wages and tips are subject to additional medicare tax withholding
- Qualified small business payroll tax credit for increasing research activities
You do not need to file a 941-X Form if your errors relate to the number of employees who received wages or Part 2 of Form 941.
How to Fill Out Form 941-X?
To fill out Form 941-X, follow the step-by-step instructions below:
- Complete the basic information, including your EIN, name, the quarter you are filing for, the company name, and the calendar year.
- Check the appropriate calendar year and the date when you discovered errors.
- Part 1: Choose whether you are correcting the underreported or overreported tax amount. Check the box on line 1 to correct underreported taxes and overreported taxes. You can check the box on line 2 for the claim process.
- Part 2: If the corrections are related to underreported taxes, check Box 3. Lines 4 and 5 are for requesting a refund and reimbursement for the overcollection of taxes from the employees.
- Part 3: Enter the corrections that need to be corrected on the previously filed Form 941.
- Part 4: If any corrections are entered on lines 7- 26c, lines 28 - 31a, or lines 32- 40, you must check the box on line 41. If you have reclassified employees as non-employees, check the box on line 42 and provide the detailed explanation
on line 43. - Part 5: Finally, provide your signature in Part 5.
Click here to get more detailed line-by-line instructions to fill out Form 941-X.
How to Correct a Previously Filed Schedule B?
If a previously filed Schedule B (Form 941) has incorrect liability dates or amounts, the correction process depends on whether the error changes the total tax liability and whether an amended Form 941-X is required.
If the Total Tax Liability Does Not Change
If the error is limited to the liability dates or amounts reported on Schedule B and does not change the total tax liability, Form 941-X generally isn't required. Follow the IRS instructions for filing an amended Schedule B.
If the Total Tax Liability Changes
If the correction changes the total tax liability, Form 941-X may be required along with an amended Schedule B, depending on the circumstances.
- Tax decrease: An amended Schedule B may be filed with Form 941-X if an FTD penalty was assessed. The corrected Schedule B must match the corrected tax reported on Form 941-X.
- Tax increase: You generally don't need an amended Schedule B for a timely correction unless an FTD penalty was assessed because the Schedule B was incorrect, incomplete, or missing.
Click here for more information about how to correct Form 941 Schedule B.
When is the deadline for filing Form 941-X?
There is no specific deadline for filing Form 941-X. You must file this form when you find any errors in your previously submitted Form 941. However, a time frame is applicable to report overreported and underreported taxes.
The IRS calls this time frame a “period of limitations.” For the period of limitations, 941 Forms for a calendar year are considered filed on April 15 of the succeeding year, even if they were filed before that date.
- For overreported taxes, you should file Form 941-X within 3 years of the date that the original Form 941 was filed or 2 years from the date you paid the tax reported on Form 941.
- For underreported taxes, you should file Form 941-X within 3 years of the date that the original Form 941 was filed.
How to File Form 941-X?
Form 941-X can be filed electronically for quick and secure processing of your amended 941 return. TaxBandits, an
IRS-authorized e-file provider, allows eligible filers to prepare and e-file Form 941-X online to correct errors on a previously filed Form 941.
Form 941-X corrections for tax years before 2024 must be filed on paper and mailed to the IRS. To check where to mail your amended Form 941, click here.
Don’t Let Form 941 Mistakes Cost You!
With TaxBandits, you can file Form 941-X quickly, with guided help and no guesswork. Fix errors and stay compliant,
on time.
- Late or incorrect filings = IRS penalties.
- Form 941 correction using Form 941-X made simple
- E-file your 941-X in minutes—no paperwork.
Where to mail Form 941-X?
If you choose to mail a paper Form 941-X, send your completed Form 941-X to the mailing address shown in the table below:
| If you are in | Use this mailing address |
|---|---|
| Connecticut, Delaware, District of Columbia, Florida, Georgia, Illinois, Indiana, Kentucky, Maine, Maryland, Massachusetts, Michigan, New Hampshire, New Jersey, New York, North Carolina, Ohio, Pennsylvania, Rhode Island, South Carolina, Tennessee, Vermont, Virginia, West Virginia, Wisconsin |

Department of the Treasury |
| Alabama, Alaska, Arizona, Arkansas, California, Colorado, Hawaii, Idaho, Iowa, Kansas, Louisiana, Minnesota, Mississippi, Missouri, Montana, Nebraska, Nevada, New Mexico, North Dakota, Oklahoma, Oregon, South Dakota, Texas, Utah, Washington, Wyoming |
Department of the Treasury |
| No legal residence or principal place of business in any state |
Internal Revenue Service |
| Special Filing Addresses for exempt organizations; federal, state, and local governmental entities; and Indian tribal governmental entities regardless of location |
Department of the Treasury |
| If you use a private delivery service to send your Form 941-X from any location to the IRS, it should be delivered to: |
Ogden – Internal Revenue Submission Processing Center
|
Are there any penalties related to filing Form 941-X?
Typically, correcting an underreported amount using Form 941-X will not be subject to penalties or interest if you follow
these guidelines:
- File on time (by the due date of Form 941 for the quarter in which the errors are discovered),
- Pay the amount shown on Line 27 by the time you file the Form 941-X,
- Enter the date you discovered the error, and
- Explain your corrections in detail.
You are not eligible to make corrections for interest-free treatment if any of the following apply.
- The underreported taxes are related to an issue raised in an examination of a prior period.
- You knowingly underreported your employment tax liability.
- You received a notice and a demand for payment.
- You received a Notice of Determination of Worker Classification.
Share this article
Need to Amend Form 941? We’re Here to Help!
- File Form 941-X—even if you didn’t file the original 941 with us.
- Step-by-step guidance through the correction process
- Live expert support included
Error?→ Fix → Submit
Related Blogs for Form 941-X
Related Topics
IRS Form 941
- Form 941
- Form 941 Instructions
- Form 941 Due Dates
- Form 941 Mailing Address
- Form 941 Schedule B
- Form 941 Penalty
- Form 941 ERC
- Form 940 vs 941
- Form 941 vs 944
Revised Form 941 for 2023
Form 941 Worksheets
- Form 941 Worksheet 4 for Q3 & Q4 2021
- Form 941 Worksheet 2 for Q2 2021
- Form 941 Worksheet 1
- Form 941 Worksheets
Form 941-X
Revised Form 941 for 2022
Revised Form 941 for 2021
- IRS Form 941 for Q4 2021
- Revised Form 941 for 2nd Quarter, 2021
- Form 941 Quarter 2 vs Quarter 1, 2021
- Revised Form 941 Schedule R for Q2 2021
- Revised Form 941 for 1st Quarter, 2021

