 BanditAI
File Rhode Island Payroll
Taxes in Minutes
Stay compliant with new-hire reporting, withholding, and
unemployment insurance taxes.

Form NHR
Deadline: Within 14 days of hire

Form RI-941
Deadline: Apr 30, Jul 31, Oct 31,
Jan 31

Form TX-17
Deadline: Apr 30, Jul 31, Oct 31, Jan 31
Rhode Island Filing Requirements for New Hire, Withholding, and Unemployment
Stay compliant with Rhode Island's new hire, withholding, and unemployment filing requirements—on time, every time.
| Forms | Filing Requirements | Filing Methods | Due Date |
|---|---|---|---|
| New Hire Report | All Rhode Island employers must report newly hired, rehired, or recalled employees. This includes private businesses, nonprofits, and government entities. |
|
Within 14 days of the employee's hire or rehire date. If you are reporting electronically or magnetically, you must report by two monthly transmissions (if necessary), not less than 12 or more than 16 days apart. |
|
Withholding (Form RI-941) |
All employers who withhold Rhode Island state income tax must file Form RI-941 quarterly, even if no tax was withheld. |
|
Additional Filing Option: Monthly filers may use Form WTM/RI-941M for non-quarter months. Due date is the 20th day of the following month. |
| Unemployment Insurance (TX-17) | All Rhode Island employers with one or more employees must file quarterly to report wages and remit unemployment insurance, temporary disability insurance, and job development fund taxes. |
|
|
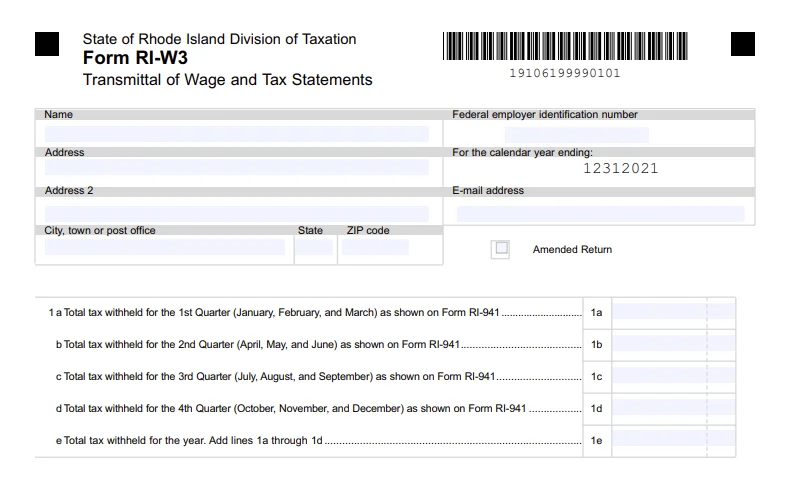
Rhode Island Annual Withholding Reconciliation Form RI-W3
Understand Rhode Island's additional filing requirements and stay compliant.
| Filing Requirement | Used to reconcile total Rhode Island income tax withheld during the year with payments submitted via Form RI-941. Reconciles exactly with the Forms W-2 issued to employees. |
|---|---|
| Due Date | January 31st of the following year. |
| What to Include | Summary of total wages, total tax withheld, and total payments made. Must accompany employee Forms W-2. |
| Filing Method | Electronic filing via the RI Tax Portal is strongly recommended. When e-filing W-2s electronically, a separate paper Form RI W-3 is generally not required. |
Information Required to File
Know what information you need to file Rhode Island payroll forms accurately.

What to Report in New Hire?
- Employee's legal full name
- Employee's physical address
- Social Security Number (SSN)
- Date of hire
- FEIN, employer name & address
- State of hire (for multi-state employers)

What to Report in Form RI-941?
- Business name and address
- FEIN and Rhode Island withholding account number
- Total wages paid during the period
- Amount of Rhode Island income tax withheld from wages

What to Report in Form TX-17?
- Employee name, SSN, and gross wages paid during quarter
- Taxable wages
- Monthly employment counts (full-time and part-time workers)
- Business name and RI UI Account Number
- FEIN
- UI tax rate and contribution amounts
Penalties and Corrections for New Hire, Withholding, and Unemployment
Know the penalties and how to correct errors before they impact compliance.
| Form | Penalties | Corrections |
|---|---|---|
| New Hire Report |
|
Corrections should be made through the Rhode Island New Hire Reporting Directory.
Phone: (888) 870-6461 for assistance. |
| Form RI-941 |
|
If an error is found (e.g., underreported wages or incorrect withholding amounts), file an amended return through the RI Tax Portal (preferred) or by paper. Any additional tax due must be paid along with applicable penalties and interest. Contact the RI Division of Taxation at (401) 574-8941 for assistance. |
| Form TX-17 |
|
Amendments must be submitted on paper with a letter of explanation. Download a new TX-17, complete corrected sections, attach explanation letter + payment (if any), and mail to RI DLT Employer Tax Section.
Note: Large employers (200+ employees) or payroll providers may file amendments electronically — call (401) 574-8700 for assistance. |
Let TaxBandits Make Your Rhode Island Payroll Filing Easy
We offer a comprehensive solution to meet all your state payroll compliance needs.
- New Hire Reporting
- Form RI-941
- Form TX-17
Frequently Asked Questions
Register at www.ri-newhire.com using your FEIN and a valid email address. Log in and submit new hire information electronically. You can also call (888) 870-6461 or fax (888) 430-6907 or mail to Rhode Island State Directory of New Hires, PO Box 335, Holbrook, MA 02343.
Rhode Island employers must report new hires within 14 days of the hire, rehire, or recall date. Electronic filers must submit two monthly transmissions no more than 16 days apart. This applies to full-time, part-time, and temporary employees.
Employers who fail to report on time may be fined $25 per employee. If the employer and employee conspire to avoid reporting or provide false information, the penalty increases to up to $500 per employee.
Form RI-941 is due on the last day of the month following each quarter end. Quarter 1 is due April 30, Quarter 2 is due July 31, Quarter 3 is due October 31, and Quarter 4 is due January 31.
Yes. Electronic filing is mandatory for employers with average monthly withholding of $200 or more. File through the RI Division of Taxation portal at tax.ri.gov. Smaller filers may submit paper returns by mail.
Rhode Island assesses interest at the federal short-term rate + 4%, compounded daily. If electronic filing is required but not completed, a 5% penalty on unpaid tax applies (capped at $500).
Form TX-17 is due quarterly: Quarter 1 is due April 30, Quarter 2 is due July 31, Quarter 3 is due October 31, and Quarter 4 is due January 31.
Yes. Rhode Island employers must file Form TX-17 every quarter, even if no wages were paid. Failure to file may result in penalties.
Rhode Island assesses a $25 penalty for each failure to file the quarterly wage information report. An additional $25 penalty is assessed for each month the report is delinquent (maximum $200 per report). A $10 penalty applies for failure to file the tax report. Interest accrues at 1.5% per month on any unpaid balance.
Form RI-W3 is due January 31st of the following year. It reconciles total Rhode Island income tax withheld during the year with payments submitted via Form RI-941.
If an error is found on your Form RI-941, file an amended return through the RI Tax Portal (preferred) or by paper. Include a clear explanation of the error and pay any additional tax due along with applicable penalties and interest. Contact the RI Division of Taxation at (401) 574-8941 for assistance.
Amendments must be submitted on paper with a letter of explanation. Download a new TX-17, complete the corrected sections, attach the explanation letter and any payment due, and mail to the RI DLT Employer Tax Section. Large employers (200+ employees) or payroll providers may file electronically—call (401) 574-8700 for assistance.
Success Starts with TaxBandits
The Smart Business Owners Choice

