 BanditAI
File Kansas Payroll
Taxes in Minutes
Stay compliant with new-hire reporting, withholding, and
unemployment insurance taxes.

Form K-CNS 436
Deadline: Within 20 days of hire

Form KW-5
Deadlines: Varies by filing frequency

Form K-CNS 100
Apr 30, Jul 31, Oct 31, Jan 31
Kansas Filing Requirements for New Hire, Withholding, and Unemployment
Stay compliant with Kansas's new hire, withholding, and unemployment filing requirements — on time, every time.
| Forms | Filing Requirements | Filing Methods | Due Date |
|---|---|---|---|
|
New Hire Report (Form K-CNS 436) |
All Kansas employers must report newly hired, rehired, or recalled employees (including those separated for 60+ consecutive days). This includes private businesses, nonprofits, and government entities. |
|
Within 20 business days of the employee's hire or rehire date. |
|
Withholding (Form KW-5) |
All employers who withhold Kansas state income tax must file Form KW-5 for each reporting period, even if no tax was withheld. |
|
Due dates depend on your assigned filing frequency:
|
|
Unemployment Insurance (Form K-CNS 100) |
All Kansas employers with one or more employees must file quarterly to report wages and remit unemployment insurance tax. Employers with 50+ employees or third-party administrators with 50+ client employees must file electronically. |
|
|
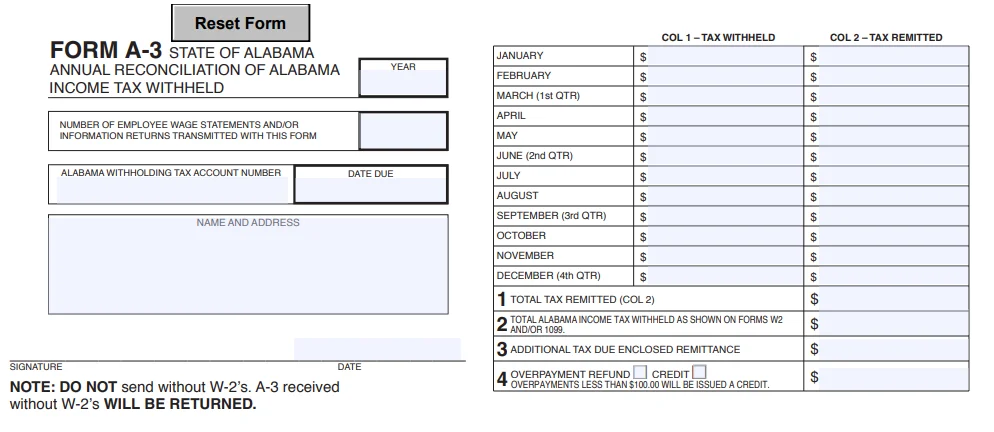
Kansas Annual Withholding Reconciliation Form KW-3
Understand Kansas's additional filing requirements and stay compliant.
| Filing Requirement | Used to reconcile total Kansas income tax withheld during the year with payments submitted via Form KW-5. Reconciles with Forms W-2 issued to employees. |
|---|---|
| Due Date | January 31st of the following year. |
| What to Include | Summary of total wages, total tax withheld, and total payments made. Must accompany employee Forms W-2. |
| Filing Method | Electronic filing via Kansas Department of Revenue is strongly recommended. When e-filing W-2s electronically, a separate paper Form KW-3 is generally not required. |
Information Required to File
Know what information you need to file Kansas payroll forms accurately.

What to Report in New Hire (Form K-CNS 436)?
- Employee's legal full name
- Employee's physical address
- Social Security Number (SSN)
- Date services first performed
- FEIN, employer name & address
- State of hire (for multi-state employers)

What to Report in Form KW-5?
- Business name and address
- FEIN and Kansas withholding account number
- Total wages paid during the period
- Amount of Kansas income tax withheld from wages

What to Report in Form K-CNS 100?
- Employee name, SSN, and gross wages paid during quarter
- Taxable wages
- Monthly employment counts (full-time and part-time workers)
- Business name and Kansas unemployment account number
- FEIN
- Unemployment tax rate and contribution amounts
Penalties and Corrections for New Hire, Withholding, and Unemployment
Know the penalties and how to correct errors before they impact compliance.
| Form | Penalties | Corrections |
|---|---|---|
| New Hire Report |
|
To correct or update a previously submitted new hire report, employers must contact the Kansas New Hire Directory directly. Corrections generally cannot be made through the standard online portal once processed.
|
| Form KW-5 (Withholding) |
Late Payment Penalties:
|
If an error is found (e.g., underreported wages or incorrect withholding amounts), file an amended KW-5 by paper form. Mark an X in the box marked "Amended Return" and report the corrected amount on line 1. Include a letter explaining the error. Any additional tax due must be paid along with applicable penalties and interest.
Contact the Kansas Department of Revenue at 785-368-8222 for assistance. |
| Form K-CNS 100 (Unemployment Insurance and wage report) |
|
Amendments must be submitted using Form K-CNS 111 (Adjustment to Quarterly Wage Report) with a letter of explanation. Mail to Kansas Department of Labor, P.O. Box 400, Topeka, KS 66601-0400.
Note: Employers with 50+ employees may file amendments electronically — call (785) 296-5000 for assistance. |
Let TaxBandits Make Your Kansas Payroll Filing Easy
We offer a comprehensive solution to meet all your state payroll compliance needs.
- New Hire Reporting
- Form KW-5
- Form K-CNS 100
Frequently Asked Questions
Register at ksnewhire.ks.gov using your FEIN and a valid email address. Log in and submit new hire information electronically. You can also call (888) 219-7798 or fax (888) 219-7798 or mail to P.O. Box 3510, Topeka, KS 66601-0400.
Kansas employers must report new hires within 20 business days of hire, rehire, or recall date. Electronic filers must submit two monthly transmissions no more than 16 days apart. This applies to full-time, part-time, and temporary employees.
Employers who fail to report on time may face federal penalties up to $25 per employee, with maximum penalties reaching $500 per month per employer.
Form KW-5 is due on the last day of the month following each quarter end. Quarter 1 is due April 30, Quarter 2 is due July 31, Quarter 3 is due October 31, and Quarter 4 is due January 31.
Electronic filing is recommended for all employers. Certain filers may be required to file electronically. File through the Kansas Department of Revenue Customer Service Center at ksrevenue.gov. Smaller filers may submit paper returns by mail.
Kansas assesses interest at 8% per annum (0.67% per month). Penalties escalate: 2% if 1–5 days late, 5% if 6–15 days late, 10% after 15 days, and 15% if unpaid 10+ days after formal notice.
Form K-CNS 100 is due quarterly: Quarter 1 is due April 30, Quarter 2 is due July 31, Quarter 3 is due October 31, and Quarter 4 is due January 31.
Yes. Kansas employers must file Form K-CNS 100 every quarter, even if no wages were paid. Failure to file may result in a minimum $25 penalty.
Kansas assesses a minimum $25 penalty for failure to file. Interest accrues on any unpaid balance. Late filing triggers additional penalties even when the tax amount is small.
Form KW-3 is due January 31st of the following year. It reconciles total Kansas income tax withheld during the year with payments submitted via Form KW-5.
If an error is found on your Form KW-5, file an amended return through the Kansas Department of Revenue (preferred) or by paper. Include a clear explanation of the error and pay any additional tax due along with applicable penalties and interest. Contact the Kansas Department of Revenue at (785) 296-3081 for assistance.
Amendments must be submitted using Form K-CNS 111 with a letter of explanation. Mail to Kansas Department of Labor, P.O. Box 400, Topeka, KS 66601-0400. Large employers (50+ employees) may file amendments electronically—call (785) 296-5000 for assistance.
Success Starts with TaxBandits
The Smart Business Owners Choice

