 BanditAI
File Ohio Payroll Taxes
Online in Minutes
Easily file Ohio payroll tax forms, including new hire reports and unemployment insurance wage reports—all from one secure platform.

Form NHR
Deadline: Within 20 days of hire

Form IT-501
Deadline: depends on assigned filing frequency

Form JFS-20125
Deadline: Apr 30, Jul 31, Oct 31, Jan 31
Ohio Payroll Filing Requirements for New Hire, Withholding,and
Unemployment Insurance
Stay compliant with Ohio payroll reporting requirements for new hires, employer withholding, and unemployment insurance.
| Forms | Filing Requirements | Filing Methods | Due Date |
|---|---|---|---|
| New Hire Report |
Ohio employers must report newly hired employees and applicable contractors who reside, work, or will be assigned to work in Ohio. |
|
Within 20 days of the employee's hire date or when an applicable contractor is engaged or re-engaged. |
| Form IT-501 - Employer's Return of Income Tax Withheld |
Employers use Form IT-501 to report and pay Ohio income tax withheld for the applicable filing period. The filing frequency is determined based on the employer's withholding liability. |
|
The deadline to file Form IT-501 depends on the employer's assigned filing frequency:
|
| Form JFS-20125 - Unemployment Compensation Quarterly Tax Return |
Employers subject to Ohio unemployment insurance must file quarterly wage and contribution reports. The return reports the wages and other employment information required for determining unemployment insurance contributions. The JFS-20125 contains the quarterly wage detail and summary reporting. |
|
The deadline to file Form JSF-20125 is the last day of the month following the end of each calendar quarter.
|
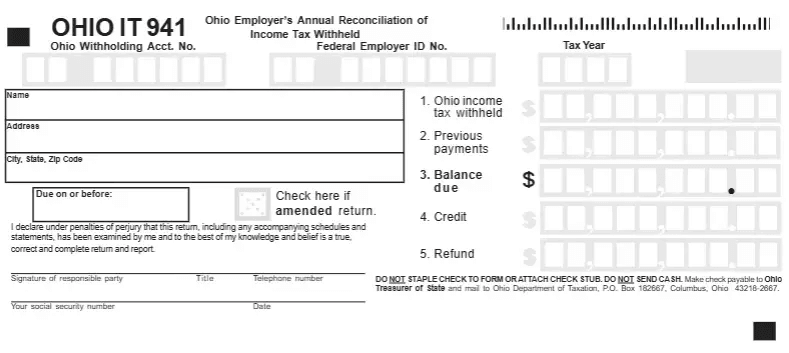
Ohio Annual Withholding Reconciliation - Form IT-941
Understand Ohio’s annual reconciliation requirements and stay compliant.
| Filing Requirement |
Every employer required to withhold Ohio income tax from employee wages must file Form IT-941 – Employer's Annual Reconciliation of Income Tax Withheld each year to reconcile the Ohio income tax withheld and payments reported during the calendar year. |
|---|---|
| Due Date |
January 31 following the end of the Note: If January 31 falls on a weekend or legal holiday, the return is due on the next business day. |
| What to Include |
|
| Filing Method |
Electronically (Recommended): Submit Form IT-941 through Ohio's electronic tax filing system. |
Information Required to File OH New Hire Report, Form IT-501, and Form JFS-20125
Know what information you need to file Ohio payroll forms accurately.

What to Report in a
New Hire?
- Employee's full name
- Employee's address
- Employee's date of birth
- Employee's Social Security Number (SSN)
- Employee's date of hire
- State of hire
- Employer's name, address, and
identification number - Date services were first performed for pay,
where applicable

What to Report on Form
IT-501?
- Ohio employer withholding account information
- Ohio income tax withheld for the
reporting period - Applicable school district income tax withheld
- Payment of the amount due

What to Report on Form JFS-20125?
- Ohio unemployment account information
- Employer identification information
- Employee names and Social
Security Numbers - Total remuneration/wages for
the quarter - Taxable wages subject to unemployment insurance
- Employee wage information required for the quarterly report
Penalties and Corrections for New Hire, Withholding,
and Unemployment Insurance
Know the penalties and how to correct errors before they impact compliance.
| Form | Penalties | Corrections |
|---|---|---|
| New Hire Report |
A penalty of up to $25 per newly hired employee may apply for failure to report. If the employer and employee conspire not to report, the penalty may be up to $500 per newly hired employee. |
Correct the employee or contractor information through the Ohio New Hire Reporting Center using the available reporting methods. |
| Form IT-501 |
Late Filing Penalty
Late Payment Penalty
Withheld but Not Remitted
|
If you identify an overpayment or underpayment on Form IT-501 during the current year, the correction can be made on a subsequent IT-501 filing or payment, as applicable.
|
| Form JFS-20125 |
Late Filing Penalty
Late Payment
|
If a previously filed quarterly report contains incorrect information, employers should amend the report through the Ohio unemployment insurance system or follow ODJFS instructions for correcting the filing. |
Let TaxBandits Make Your Alaska Payroll Filing Easy
We offer a comprehensive solution to meet all your state payroll compliance needs.
- New Hire Reporting
- Form TQ01C
Frequently Asked Questions
Employers must submit an Ohio New Hire Report within 20 days of hiring an employee or engaging or re-engaging an applicable contractor.
Ohio employers must report newly hired and rehired employees to the Ohio New Hire Reporting Center. The reporting requirement also applies to applicable contractors who reside, work, or are assigned to work in Ohio. Employers must report the required information within the specified reporting timeframe.
Ohio employers use Form JFS-20125, Unemployment Compensation Quarterly Tax Return, to report quarterly unemployment insurance information. It includes employee wage details and a quarterly summary used to report the employer's unemployment compensation wages and contributions.
Form JFS-20125 is filed quarterly and is due on the last day of the month following each calendar quarter.
| Quarter | Due Date |
|---|---|
| Q1 | April 30 |
| Q2 | July 31 |
| Q3 | October 31 |
| Q4 | January 31 |
Form JFS-20125 includes employee wage detail and a quarterly summary for Ohio unemployment compensation reporting. Employers report the applicable quarterly wage information and unemployment compensation amounts.
An employer that fails to make a required new hire report may be subject to a $25 civil penalty for each failure. The penalty may increase to $500 per failure when the failure results from a conspiracy to avoid reporting or provide false or incomplete information.
Yes. If information in a submitted New Hire Report needs to be corrected, the employer can submit the updated information through the Ohio New Hire Reporting Center.
Ohio employers subject to unemployment insurance reporting must file Form JFS-20125 quarterly. The report provides the wage details for employees and a summary of the employer's unemployment insurance wages and contributions for the reporting period.
The due date for Form IT-501 depends on the employer's assigned withholding filing frequency. Quarterly filers must file by the last day of the month following the quarter, while monthly filers must file within 15 days after the end of the month. Applicable partial-weekly filers must make payments within three banking days after the applicable payroll period.
Ohio employers may file Form IT-501 quarterly, monthly, or partial-weekly, depending on their withholding liability. The filing frequency is determined during registration and re-evaluated for each calendar year.
Form IT-501 is used to report and pay Ohio income tax withheld for the applicable filing period. Employers do not need to file it when there is no Ohio income tax liability for the period.
Success Starts with TaxBandits
The Smart Business Owners Choice